We did it!
Kristin announced that her household had paid off its last credit card, completing a debt journey that began around September 2005.
Read MoreKlingtocash is a personal finance and frugal living blog for readers who want to take control of household spending, reduce expenses, and work toward financial freedom.
Written by Kristin L. Ingram, CPA. In 2012, she paid off $70,000 in credit card debt after a journey that began around September 2005. Her practical guidance covers budgeting, debt payoff, increasing income, reducing expenses, and affordable recipes.
Kristin announced that her household had paid off its last credit card, completing a debt journey that began around September 2005.
Read More
A look at why Kristin's household canceled its credit cards after becoming debt-free, and the considerations behind that decision.
Read More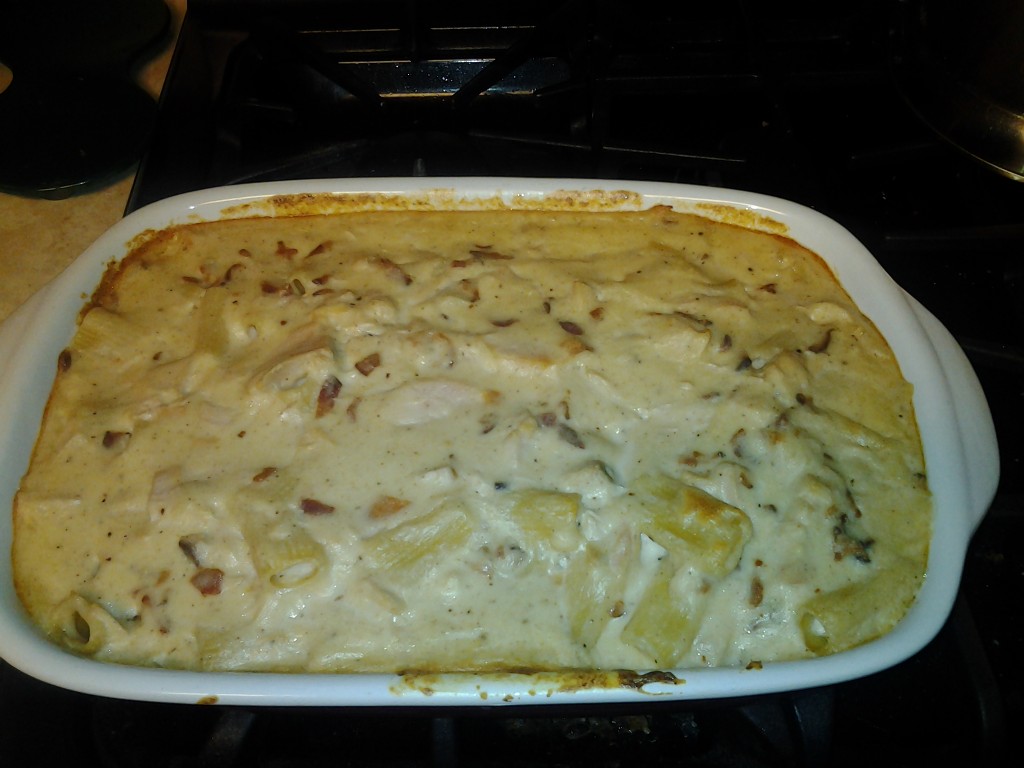
Practical ways to reduce food costs by preparing meals at home, including budget-friendly recipes such as Build Your Own Casserole and Corn Chowder.
Read More
Kristin explores how careful attention to food spending and everyday habits can support a more budget-conscious approach to weight loss.
Read More
Guides for creating a budget, avoiding common mistakes, organizing monthly bills, and using percentages to help stay motivated toward financial goals.
Read More
Ideas for earning more through raising your salary, using your skills effectively, and exploring additional employment opportunities.
Read MoreSubscribe for new posts on saving money, paying off debt, frugal meals, and practical ways to manage household expenses.
Klingtocash is a personal finance blog focused on the everyday mechanics of getting ahead with money. The writing centers on budgeting, tracking monthly spending, paying down credit card balances, and building a plan that survives contact with real life. Rather than promising quick fixes, the site treats money management as a set of repeatable habits: write down what you spend, look for waste you can cut, and know exactly where each payment is going before the month ends.
Debt payoff forms the spine of the site. Much of the guidance explores how to choose between strategies like the debt avalanche and the snowball method, how to call a credit card company and ask for a lower interest rate, and how to redirect freed-up minimum payments toward the balance that costs you the most. The tone is practical and encouraging, aimed at people who feel stuck and unsure where to begin.
A recurring theme is the idea of paying yourself first. Instead of saving whatever happens to be left over at the end of the month, the site suggests automatically setting aside a small amount right when income arrives, then treating that money as already spent. This simple switch in mindset, paired with an emergency fund and clear savings goals, is presented as the foundation for making progress on debt and eventually reaching a more comfortable financial life.
Budgeting advice here leans toward tools that are simple enough to maintain. Spreadsheets, paper lists, and everyday apps all get discussed, along with the value of doing a quick weekly check-in rather than a painful yearly audit. The emphasis is on consistency: a budget you actually follow beats a perfect system you abandon, so the advice focuses on small adjustments that are easy to keep, like cooking at home more often or reviewing subscriptions you no longer use.
The blog also spends time on the earning side of the equation. Conversations with your boss, negotiating a raise, and thinking about whether a side job or extra income stream fits your schedule all appear as ways to increase what you bring home each month. The argument is that cutting expenses alone rarely closes the gap, and that learning to ask clearly for what you are worth is a skill worth practicing and refining over time.
Everyday spending gets a close look, with particular attention to the categories that quietly drain a household budget: groceries, dining out, car costs, and impulse purchases picked up while errands take longer than expected. The site frames frugal choices as shortcuts to bigger goals rather than as punishment, and notes that most people can find meaningful savings with a few deliberate swaps instead of a total lifestyle overhaul.
Life and money goals are treated as companions rather than opponents. Posts connect paying off debt to retiring sooner, building a buffer against emergencies, and having options when unexpected bills arrive. There is attention to the emotional side of money too: the stress of a job change, the temptation to lean on credit, and the encouragement that comes from watching a balance fall month after month because a plan is finally working.
Readers are frequently reminded of the small decisions that shape results over years. Skipping a purchase you do not need, checking an interest rate, renegotiating a bill, or setting a short deadline for a savings goal can look insignificant in the moment but compound steadily. The site encourages writing goals down, revisiting them regularly, and treating setbacks as ordinary course corrections rather than evidence that the plan was wrong.
Klingtocash is written from experience. The author, a CPA, describes paying off a substantial amount of credit card debt after years of trial and error, and the blog keeps that history in view as a source of credibility and relatability. Rather than lecturing, the writing offers things that worked, things that did not, and permission to start wherever you are, with whatever you have, and adjust as life changes.
An email subscription option and reader survey are part of the site.